

UNest: Invest & Save for Kids
by UNest Holdings, Inc.
3.8
- Safety
- 100% Safe
- Category
- Finance
- Ratings
- 3.8
- Price
- Free
- Download
- 100.00K
This app is secure, reliable, free to install, and offers fast downloads without any risks or malware.
Screenshots
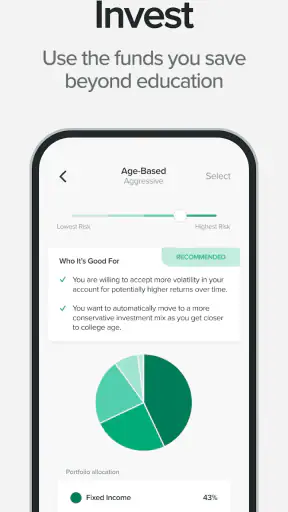
 Analysis by Getfullapps
Saving for a child sounds simple until the process involves a custodial account, investment choices, identity checks, and a parent trying to complete everything between school pickup and dinner. UNest: Invest & Save for Kids is built around that specific job: helping an adult save and invest for a child through a UTMA custodial account. I found its appeal less in flashy finance tools and more in giving family saving a clear destination.
That focus matters. This is not a general-purpose banking app, a stock-trading terminal, or a budgeting dashboard for every household expense. It is a finance app from UNest Holdings, Inc. aimed at parents and other adults who want to build money for a child over time. The app is free to install, carries an Everyone age rating, and has passed the early trial stage with more than a hundred thousand installs. Its average rating sits at 3.8 from roughly two and a half thousand ratings, which suggests a useful service with a noticeable amount of user friction rather than a universally effortless experience.
Getting past the points where setup usually slows down
The first thing I would tell a new user is not to treat account creation as a quick tap-through. A custodial investment account requires careful attention because the adult opening it is managing money for someone else. Before starting, have the child’s basic information and the responsible adult’s personal details close at hand. Even when the app itself is straightforward, mismatched spelling, an incomplete address, or uncertainty about who should be the custodian can turn a short setup into a pause.
The most important early decision is understanding what a UTMA custodial account means in everyday terms. The money is intended for the child, while the adult custodian manages it until the legal transfer point that applies in the relevant situation. That is different from putting money into an ordinary savings account in the parent’s own name. I would not begin with a deposit until I was comfortable with that ownership structure, because changing a family’s plan later can be more complicated than choosing a different savings target.
Another common sticking point is expecting the app to behave like a normal payment wallet. A child-focused investment account has more checks around it than a casual transfer app. If a screen asks for information that feels repetitive, I would slow down rather than guess. A guessed detail can create a verification mismatch, while taking a moment to compare the entry with official records is usually the safer recovery step.
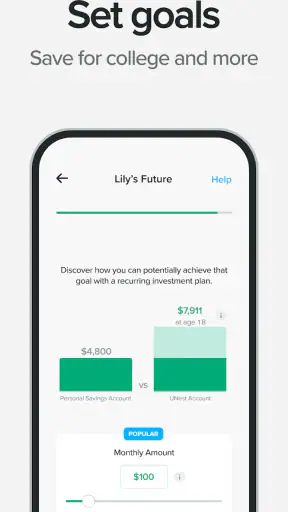
There is also a practical emotional hurdle: deciding how much to contribute. The app’s purpose can make users feel they need a large, impressive starting amount, but a sustainable family habit is more useful than an ambitious plan that gets abandoned. I prefer setting an amount that fits the household’s ordinary cash flow, then reviewing it after a few weeks. The goal is to make saving for the child repeatable, not to turn the first session into a financial performance.
Checks I would make before opening the account
I would begin by checking that the device runs at least Android 7.0 or a later release. The current version is 3.8.1, so keeping the operating system and app reasonably current is a sensible first troubleshooting step if a screen behaves oddly. I would also install it from the official app marketplace rather than relying on an old installation package. That reduces the chance of using an outdated build when the account flow has changed.
Articles to Explore Next

Uber Eats Makes Dinner Easier to Manage, but the Fees Add Up

Google Photos Turns a Camera Roll Into a Library You Can Find Your Way Through

Canva on Mobile: Adopt It for Quick Visuals, Test It for Demanding Work

Google Drive Keeps Work Moving Until It Doesn’t

Switching to Weather - By Xiaomi Means Relearning Your Forecast Routine

Ludo King and the Social Life of a Lucky Six
Next, I would make sure the adult completing the process is the person who should manage the custodial account. This sounds obvious, but families sometimes start on a shared device or with one relative’s email and then discover that the account details do not match the person who intended to take responsibility. Starting with the correct adult avoids an unnecessary restart and makes later account access easier to understand.
A stable connection is worth checking before beginning any financial form. If a page loads halfway, a confirmation button appears unresponsive, or the app returns to an earlier screen, I would avoid repeatedly tapping submit. First I would wait, check whether the previous action completed, and then reopen the relevant section. Repeated submissions can make it harder to tell whether a transaction or application step actually went through.
Notifications and email are also part of the practical setup, even though they are easy to overlook. I would check the inbox associated with the account and look in filtered folders if an expected message does not appear. I would not create a second account immediately just because one message is delayed. Duplicate sign-ups can make it unclear which profile is connected to the child’s information.
The app includes in-app purchases ranging from $4.99 to $149.99 per item. That makes it especially important to read each purchase screen instead of assuming that every part of the experience is covered by the free download. I would treat any optional payment as a separate decision and confirm the amount before approving it. For a family app, this is a small but meaningful habit: the adult should know whether a charge is a service choice, a contribution, or something else before proceeding.
What the everyday workflow feels like
In ordinary use, I would approach UNest as a scheduled family-finance routine rather than an app to open constantly. The useful workflow is to identify the child, decide on a contribution pattern, check that the account is progressing as expected, and then leave the money alone long enough for the plan to have a chance. Constantly checking short-term investment movement can create anxiety and encourage decisions that do not match the long-term purpose.
A realistic example would be a parent who wants to build a fund for future education, a first car, or another major milestone. After the account is established, that parent might review it on a quiet weekend, confirm that the intended child is selected, and verify the latest activity before making the next contribution. The key benefit is psychological: the money has a named purpose, so it is less likely to disappear into everyday spending than cash sitting in a general account.
I also see a useful role for relatives. A grandparent or another family member may want to contribute to a child’s future without becoming responsible for the entire financial plan. In that situation, the custodian should decide how contributions fit the family’s goals and should explain the arrangement clearly before sharing account details. I would avoid treating every gift as an automatic investment instruction; the adult managing the account needs to remain in control of what is appropriate.
One non-obvious advantage of a child-specific account is that it can make financial conversations concrete. Instead of telling a child that saving is important in the abstract, a parent can explain that regular contributions are being set aside for a named future purpose. The app does not replace those conversations, but it can give them a practical anchor. I would still keep the explanation age-appropriate and avoid presenting investment growth as guaranteed.
The trade-off is that a custodial account is less flexible than keeping money in the parent’s own general savings. The child is central to the account, and that structure should be treated as a commitment. If a family is still deciding whether the money might be needed for an emergency, a household bill, or a different child, I would first build that flexibility elsewhere. UNest is better suited to money that has a deliberate child-focused destination.
Recovering when the process appears to fail
When an app seems stuck, I use a simple recovery order. I first note the last screen that worked and whether any confirmation appeared. Then I check the connection, close and reopen the app, and sign back in only if necessary. If the issue remains, I update the app and restart the device before attempting the same step again. These actions sound basic, but they prevent a temporary display problem from becoming several conflicting attempts.
If a contribution appears uncertain, I would check the account activity and the payment method before trying again. The important question is whether the money actually left the account, not merely whether the button changed state. I would keep a record of the time and amount of the attempted action, without sharing sensitive information in an unsecured message. That record makes any later support conversation clearer and helps avoid duplicate contributions.
For sign-in trouble, I would confirm that I am using the original account details rather than starting a new profile. If the problem is limited to one device, trying the same account on a trusted, compatible device can help identify whether the issue is local. I would not disable security protections or hand over login information to someone offering an unofficial fix. Finance apps deserve the same caution as a bank account, even when the interface feels friendly.
When a verification step does not move forward, patience is more useful than repeated edits. I would review every field for consistency, especially names and addresses, and make sure the adult’s information is being entered where requested rather than the child’s. If the app asks for a document or confirmation, I would use a clear, current version and avoid cropped or unreadable images. The goal is to remove ambiguity, not to force the screen to accept an uncertain submission.
There is a valuable distinction between an application that is still being reviewed and an application that has failed. A delay does not automatically mean the details were rejected. I would look for an in-app status or message before changing information. Editing repeatedly can create new inconsistencies and make the original problem harder to diagnose.
When the app is not the actual problem
Some frustrations belong to the surrounding financial process rather than the application. A bank may delay a transfer, a card may decline a charge, or an identity check may require information that the user does not have immediately available. In those cases, reinstalling UNest will not solve the underlying issue. I would first identify whether the failure happened inside the app or at the payment and verification stage connected to it.
Timing can also create misleading expectations. A contribution may not appear at the exact moment it is initiated, and investment activity should not be judged like a live spending balance. If the app shows a pending state, I would give that status more weight than a temporary lack of visible movement. I would only repeat the action after confirming that it did not complete.
Investment risk is another area where the app cannot remove uncertainty. The store summary presents the service as a way to save, invest, and build wealth for children, but building wealth is not the same as promising a particular result. Markets can rise and fall, and a parent should avoid using money needed soon for essential expenses. If the family’s priority is preserving a specific amount for a near-term need, a conventional savings option may be easier to understand and more appropriate.
Taxes and account ownership are also reasons to think beyond the interface. A UTMA structure has consequences that depend on the family’s circumstances and local rules. I would not use a simple in-app explanation as a substitute for professional advice when the contribution is substantial, the family has complex tax concerns, or several relatives are involved. The app can organize the saving process, but it cannot make personal financial decisions on the user’s behalf.
Compared with a standard savings account, UNest offers a more direct child-centered purpose and an investment orientation, but it may feel less suitable for emergency access or short-term certainty. Compared with a general brokerage account, it is more focused on the custodial relationship and less oriented toward hands-on trading. Compared with a basic budgeting app, it is designed around actually setting money aside rather than merely tracking a goal. Those differences are useful only if the account structure matches the family’s intention.
Who should use it, and who should choose something else
I would recommend trying UNest to a parent who wants a dedicated long-term fund for a child and values a guided, focused experience over a broad investment toolkit. It also makes sense for an adult who has struggled to keep child-related savings separate from ordinary household spending. Giving the goal its own account can make the habit easier to maintain and easier to discuss with family members.
I would be more cautious for someone who wants complete control over individual investments, advanced research, or frequent trading. This is not the type of tool I would choose for testing sophisticated strategies. I would also look elsewhere if the main need is an emergency fund, a flexible household savings account, or a simple way to divide money among several short-term goals.
Families should think carefully before opening an account simply because the idea of investing for a child sounds appealing. The custodial arrangement is a meaningful commitment, and the adult should understand who controls the account and who the money is intended for. If that answer is unclear, a conversation with a qualified financial professional may be more valuable than rushing through setup.
My practical verdict after weighing the friction
UNest: Invest & Save for Kids has a clear purpose, and that clarity is its strongest quality. It turns the vague intention to “save for the child” into a dedicated financial task connected to a UTMA custodial account. The free app, Everyone rating, and support for Android 7.0 and later make it approachable for many families, while the current 3.8.1 release indicates that users should keep their installation updated when troubleshooting.
My reservations are equally practical. Account setup deserves careful attention, financial verification can interrupt the flow, and the custodial structure is not as flexible as ordinary savings held by a parent. The presence of in-app purchases also means I would read payment prompts closely rather than assuming the download tells the whole cost story. None of these points makes the app unusable, but they do mean it rewards deliberate users more than impatient ones.
The best way to use it is to decide the purpose first, prepare the correct adult and child details, start with a contribution that the household can maintain, and check activity calmly instead of reacting to every delay or market movement. If the goal is a long-term child fund and the account structure fits, I think this app is worth considering. If flexibility, immediate access, or hands-on investing matters more, a conventional savings product or a broader brokerage alternative may serve you better.
Overall, I see it as a focused family-finance tool rather than an all-purpose money app. I would recommend it to someone who wants structure and a child-specific destination, provided that person understands the commitment behind a custodial account. The deciding question is not whether the app can make saving feel easy; it is whether this particular account structure matches what you want the money to do.
Pros
- Automates recurring investments, making long-term saving easier.
- Provides goal-focused accounts designed specifically for children’s futures.
- Simple onboarding and a clean interface suit first-time investors.
- Offers educational resources to help families understand investing basics.
- Parents can monitor contributions and account progress in one place.
Cons
- Investment values can fall, so savings are not guaranteed.
- Fees and fund expenses may reduce returns over time.
- Account availability and features may depend on your location.
- Withdrawals may involve restrictions or affect the account’s tax benefits.
- Requires personal and financial information during registration.
FAQs for UNest: Invest & Save for Kids
What is UNest: Invest & Save for Kids, and how does it work?
UNest is a family-focused investing and savings app designed to help parents and relatives build money for a child’s future. After creating an account, you can set up recurring contributions, invite family members to participate, and invest through an account intended for the child. The app is built around long-term goals such as education, rather than everyday spending or short-term saving.
Is UNest suitable for saving for college or other long-term goals?
UNest is primarily designed for long-term planning, especially education expenses. Depending on the account structure and current product availability, contributions may be invested in a portfolio selected according to the child’s age or the chosen risk approach. Investment values can rise or fall, so UNest should not be treated as a guaranteed college fund. Review the available account options, fees, tax rules, and withdrawal conditions before investing.
Who can open a UNest account, and what information is required?
The service is generally intended for parents, legal guardians, and other eligible adults who want to save or invest for a child. During registration, users may need to provide personal identification, tax information, banking details, and information about the beneficiary. Eligibility can depend on residency, age, account type, and applicable regulations. Carefully check the current requirements in the app before starting the enrollment process.
Does UNest charge fees, and are there any investment risks?
Before downloading or funding an account, review UNest’s current pricing carefully. Depending on the plan and services available, users may encounter subscription charges, management fees, fund expenses, or other account-related costs. Investments are not risk-free: market declines can reduce the account balance, and past performance does not guarantee future results. Fees, contribution limits, tax treatment, and withdrawal rules may also vary.
Can family members and friends contribute money through UNest?
One of UNest’s useful features is the ability to involve relatives and friends in a child’s savings journey. Parents or account owners can typically share a contribution link or invitation so others can make gifts without managing the entire investment account. Contribution methods, limits, verification requirements, and gift rules may change, so confirm the current process and make sure contributors understand where their money is going.

UNest: Invest & Save for Kids
This site provides independent information about third-party apps and is not affiliated with, or the owner, developer, or distributor of, any app featured here. App names, logos, and trademarks belong to their respective owners. Developer details are provided for reference; please contact the developer directly via support@unest.co, visit https://unest.co/, or review their https://www.unest.co/privacypolicy/.










